Non-Alcoholic Beverage Growth: Insurance Risks Brands Should Plan For
Non-alcoholic beverage growth is creating new opportunities and new insurance questions around product liability, recalls, distribution, and contracts.
Todos los artículos
Three M&A Deals, Three Outcomes: The Cost of Insurance You Didn't Know You Needed
Three real M&A case studies: one deal RWI saved, one claim it paid, and one cautionary tale where the absence of insurance cost the seller everything he had just earned.

Should I File This Claim — Or Just Pay Out of Pocket? A CT Agent's Honest Framework
Before you call your carrier — read this. A Connecticut independent agent walks through the real claim-versus-pay-out-of-pocket framework, including the CLUE report trap, the 3-year premium math, and when filing is absolutely the right call.
From LOI to Closing: When Does R&W Insurance Fit Into Your M&A Timeline?
A week-by-week view of how Representations and Warranties Insurance fits into the M&A deal timeline, from Letter of Intent to bound policy. Underwriting calls, exclusions, and fast-track programs.
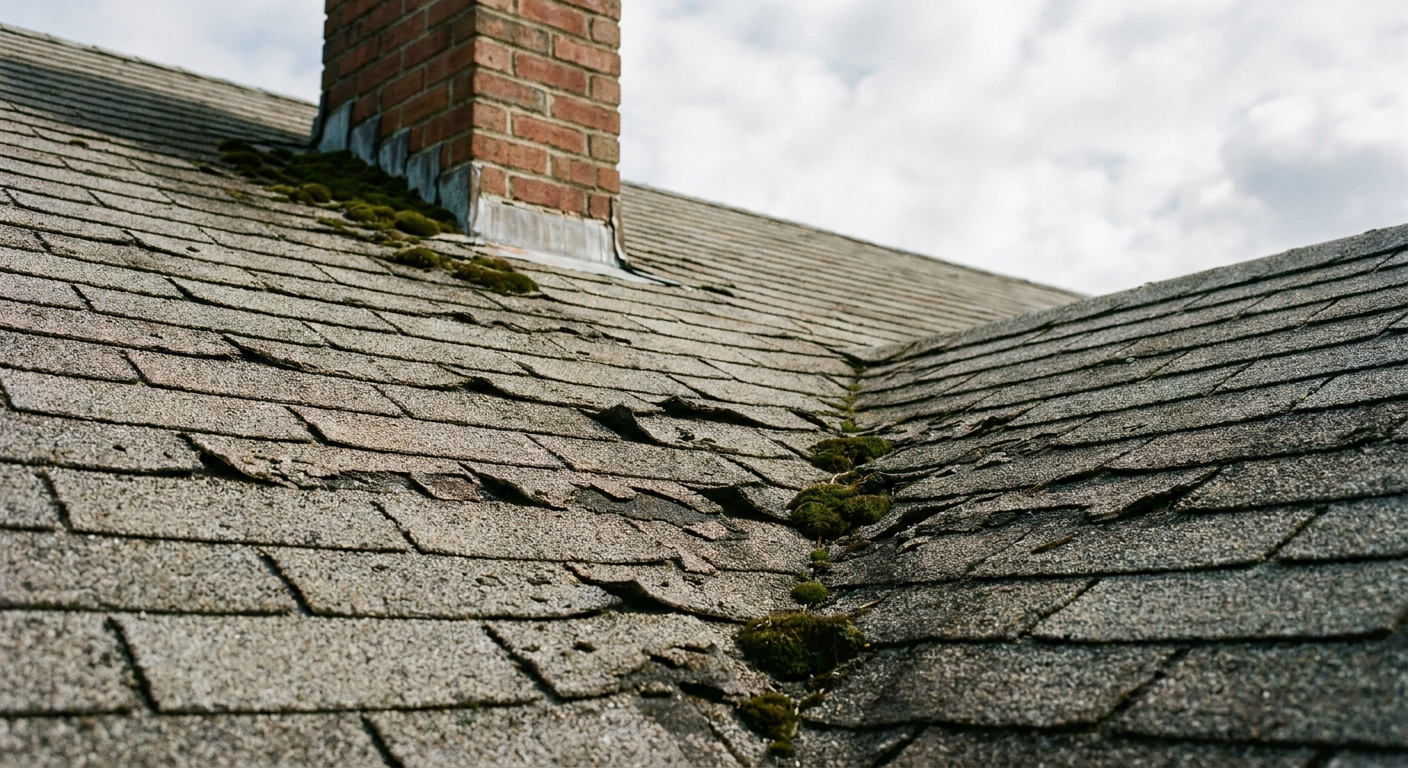
Actual Cash Value vs. Replacement Cost on Your Connecticut Roof: The Decision That Costs Thousands
ACV or RCV on your roof is the single most consequential line item on a Connecticut homeowners policy in 2026. See the real claim math, learn which carriers still offer Replacement Cost on 15-plus year roofs, and know exactly how to check your declarations page.
Selling Your Business? Walk Away Clean With Transactional Liability Insurance
For sellers, RWI means a smaller escrow, clean proceeds at closing, and protection from innocent breaches. Here is how Seller Protect works and why it has become standard for exit planning.
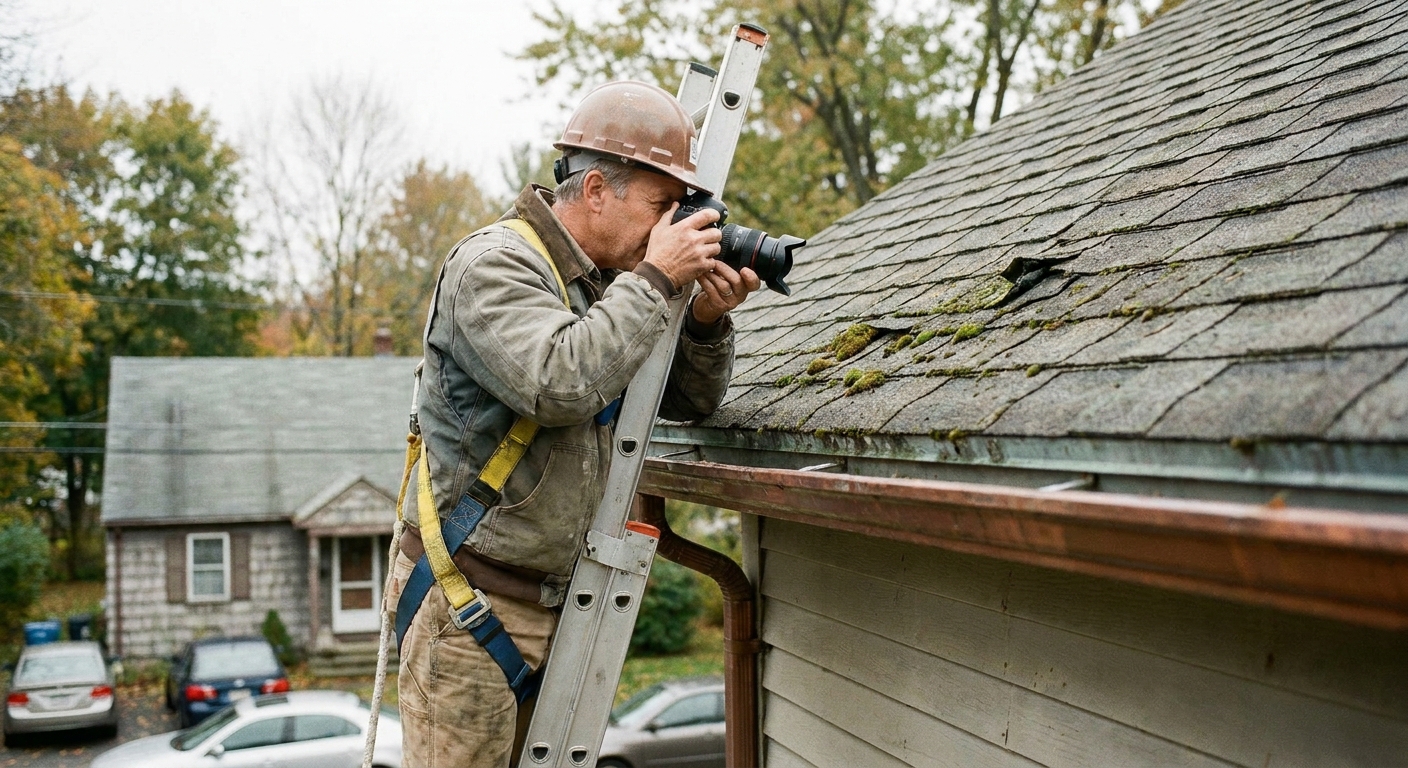
Your Insurer Wants a 4-Point Inspection and Roof Photos — Can They Drop You?
Connecticut insurers are inspecting more homes than ever. What triggers a 4-point inspection, what inspectors actually look for, your rights under CT law, and the practical playbook to pass — and what to do if the report comes back with issues.
Buying a Business? How R&W Insurance Protects You From Hidden Liabilities
Even thorough due diligence misses things. Here are the five most common post-closing surprises buyers face, why personal seller indemnities fail, and how RWI changes the math for acquirers.
Do You Really Need an Umbrella Policy If You Have $300,000 in Liability?
The $1 million umbrella threshold explained. Why $300,000 in underlying liability is not enough in Connecticut in 2026, how much umbrella coverage you actually need, and the surprising things it covers.
What Is Transactional Liability Insurance? A Plain-Language Guide to RWI
Representations and Warranties Insurance explained without the jargon. How the policy is structured, what it costs, what it covers, and when tax or contingent liability insurance comes into play.
The Insurance Mistake That Can Kill Your M&A Deal
The single oversight that derails more mergers and acquisitions than anything else is not valuation or financing. It is missing transactional liability insurance. Day 1 of a seven-day series on M&A insurance.
Why Did My Connecticut Homeowners Premium Just Double?
Your house hasn't changed, but your Connecticut homeowners premium just jumped 40%, 80%, even 100%. Here's exactly why rates are spiking in 2026 — and the five moves that actually bring your premium back down.

How Do I Properly Insure High-Value Jewelry in Connecticut?
Standard homeowners policies cap jewelry coverage at $1,000-$2,500. Learn how scheduled coverage, Agreed Value, and Mysterious Disappearance protection properly safeguard your Connecticut collection.