How Shared and Layered Property Insurance Programs Work
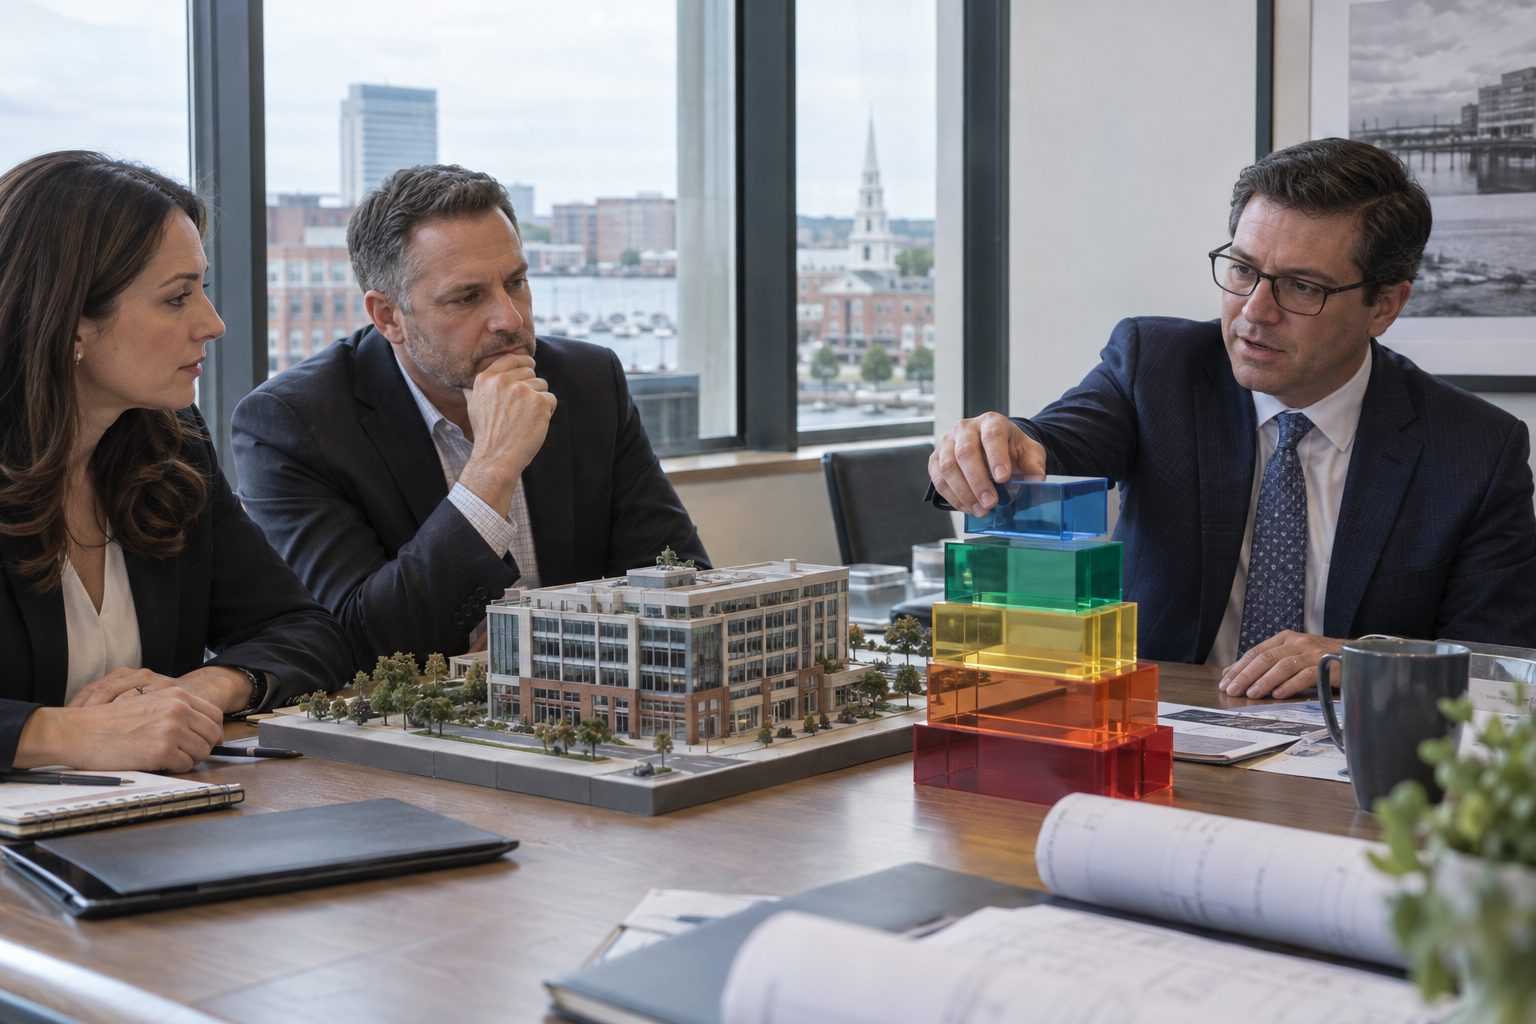
How do shared and layered property insurance programs work?
A shared property program has multiple insurers participating in the same limit or layer, while a layered program stacks insurers above one another at different attachment points. Both structures can assemble capacity for larger or more complex risks, but buyers must compare wording, deductibles, claims coordination and insurer participation—not just total limit.
One insurer does not always provide the entire amount of property coverage a business needs. Large schedules, catastrophe exposure and specialized occupancies can require several insurers to build one program. The result may look complicated, but the basic idea is familiar: divide a large job into defined pieces.
Risk Placement Services’ 2026 US Property Market Outlook describes abundant capacity and active competition, including the use of shared and layered placements. (RPS, pp. 2, 8, 12 and 14.) This iConn Insurance Solutions guide explains those structures without assuming they are right for every Connecticut account.
What is shared commercial property insurance?
In a shared arrangement, two or more insurers take stated percentages of the same limit or layer. If three insurers participate 50%, 30% and 20% in a $10 million layer, their illustrative shares of that layer are $5 million, $3 million and $2 million. That example explains structure only; it is not a quote.
A lead insurer may establish primary terms, with other participants following agreed pricing and wording. The exact contracts matter. Buyers should confirm each insurer’s participation, which terms are common and what happens if one participant changes position before binding.
What is layered commercial property insurance?
A layered program stacks limits. One insurer might cover the first portion above the deductible, and another might attach above that amount. A hypothetical $25 million program could use a $5 million primary layer, a $10 million layer above $5 million and another $10 million above $15 million.
Higher layers generally respond only after covered loss reaches their attachment points and underlying limits are exhausted as required by the contracts. That makes alignment important. A disagreement about wording or exhaustion can create friction when a loss crosses layers.
How do shared and layered programs compare?
| Structure | How capacity is arranged | Main issue to review |
|---|---|---|
| Single insurer | One insurer provides the limit | Concentration and available capacity |
| Shared | Several insurers split the same layer | Participation, common terms and coordination |
| Layered | Insurers attach at different loss levels | Attachment points, exhaustion and wording |
| Shared layers | Multiple insurers split one or more stacked layers | Both participation and layer alignment |
No structure is automatically superior. A straightforward account with enough single-insurer capacity may benefit from simplicity. A larger or catastrophe-exposed portfolio may need a more complex design to reach the desired limit or improve diversification.
What is the RPS ADAPT capacity described in the report?
On page 12, RPS describes ADAPT as proprietary capacity offering 20% participation, scalable up to $100 million on the property side for qualifying accounts. RPS says it follows the lead insurer’s pricing and terms, which is intended to support more efficient placements.
Those figures need careful interpretation:
- 20% participation refers to an insurer-capacity share, not a 20% premium discount.
- Up to $100 million is the property-side scale stated by RPS, not guaranteed capacity for every account.
- Qualifying accounts remain subject to eligibility, underwriting, structure and actual terms.
- The report does not establish that iConn has confirmed access for a particular client.
ADAPT is therefore best understood as an example of how delegated or proprietary capacity may help brokers complete a program. It should not be advertised as a universal product promise.
What can go wrong in a layered insurance program?
Misaligned wording
Layers may not treat a cause of loss, valuation issue or time-based coverage identically. Differences can become important when a large claim reaches more than one contract.
Unclear attachment points
Every participant should know where its obligation begins. Confirm whether limits are stated per occurrence, in the aggregate or differently for specific perils.
Deductible confusion
The retained amount should be modeled by location and peril. Percentage deductibles deserve a dollar illustration.
Claims coordination
Ask who leads adjustment, how participants communicate and what happens when the estimated loss moves across layers. Strong pre-loss documentation can reduce confusion.
Financial and service tradeoffs
Capacity is not the only concern. Review insurer financial strength, claims reputation, continuity and the broker’s rationale for selecting participants. RPS encourages buyers to look beyond price and consider the quality of capacity. (RPS, pp. 11–12 and 15.)
Mid-article next step: If your proposal includes multiple insurers, ask iConn for a one-page tower showing every layer, attachment point, limit and participant. You should be able to understand the design before binding.
When does a layered property program make sense?
Potential candidates include larger property schedules, concentrations of value, catastrophe-exposed portfolios and occupancies where one insurer does not want the full amount. RPS notes use of alternative structures in manufacturing and other sectors where program design can improve available capacity. (RPS, p. 8.)
Complexity should earn its keep. If a multi-insurer design does not improve available limit, terms, diversification or price enough to justify added administration, a simpler option may be preferable. The decision belongs to the actual risk, not a market trend.
What should buyers ask before accepting a multi-insurer program?
- Who is the lead insurer, and what authority does the lead have?
- Which insurers participate, at what percentages and on which layers?
- Are policy forms and key endorsements aligned?
- Where does every layer attach, and how must underlying coverage be exhausted?
- How do deductibles and sublimits apply across the program?
- Who coordinates claims and communications?
- Which requirements remain open before binding?
Request the answers in writing. A clear program diagram and quote comparison can turn an intimidating tower into a manageable buying decision.
Why independent brokers matter for complex placements
An independent broker’s role is to present the risk, test suitable structures and explain the tradeoffs. Access to many markets does not replace analysis. The broker must also coordinate accurate information and avoid gaps between participants.
iConn Insurance Solutions helps Northeast businesses evaluate single-insurer, shared and layered alternatives where appropriate. Our sister agency, Insure Connecticut LLC, offers additional Connecticut insurance resources. Actual capacity and terms depend on insurer underwriting.
Frequently Asked Questions About Shared and Layered Property Insurance
Is a layered property program more expensive?
Not necessarily. Price depends on the risk, limits, attachment points, participants and market conditions. Layering may help assemble capacity or improve competition, but it also adds coordination. Compare the complete program with a viable single-insurer alternative when one is available.
Who pays a claim in a shared program?
Each participating insurer is generally responsible for its contracted share, subject to its policy terms. The lead may coordinate parts of underwriting or claims handling, but buyers should confirm the actual arrangement. A participation schedule should identify each insurer and percentage.
Does excess property insurance mean surplus lines insurance?
Not always. “Excess” can describe a layer that attaches above underlying coverage, while “excess and surplus lines” describes a market segment. Similar words can refer to different concepts. Ask your broker to identify both the layer’s function and the insurer’s placement status.
What does RPS ADAPT’s 20% participation mean?
RPS states that ADAPT can provide 20% participation for qualifying accounts. It means a capacity share in the property program, not a premium reduction. The report also says the facility can scale up to $100 million on the property side, subject to qualification and actual terms.
How should a Connecticut owner review a layered program?
Ask for a program tower showing limits, attachment points and participants. Then compare wording, deductibles, sublimits, claims coordination and open conditions. Connecticut regulatory and placement requirements should be handled by the licensed professionals involved in the actual transaction.
Make the structure understandable before you buy
A complex program can be appropriate, but it should never be mysterious. Ask iConn Insurance Solutions to map the proposed structure and compare it with available alternatives.
Source: Risk Placement Services, 2026 US Property Market Outlook, pp. 2, 8, 11–12, 14–15. See the 2026 property market pillar guide. General educational information only; eligibility, capacity, policy language and insurer underwriting control.
Draft editorial package — remove before publication
Focus keyword: layered commercial property insurance. Secondary keywords: shared property insurance; insurance program layers; property insurance tower; RPS ADAPT capacity; multi-insurer property program; how does layered property insurance work?
Feature image placed with responsive sizes. Additional alt text: Broker mapping an insurance tower with a building model; Shared property capacity discussion; Advisor explaining layered property limits.
Editorial notes: Confirm legal review of ADAPT wording and whether any direct product reference should remain. Expansion: add an approved anonymized tower. Merge: shorten claim coordination if covered in another article. Follow-ups: excess versus surplus lines terminology and claims across multiple layers.
Contenido relacionado
AI Fraud Insurance Exclusions: Where Coverage Can Break
A large cyber limit can hide a small social engineering sublimit. Learn how voluntary-transfer language, verification conditions, and overlapping crime coverage can affect AI fraud claims.
Leer artículo →
Connecticut Builders Risk Insurance: 2026 Buyer’s Guide
Connecticut builders risk buyers should update project values, timelines and controls. Learn what to prepare and compare for a 2026 placement.
Leer artículo →
How Shared and Layered Property Insurance Programs Work
Learn how shared and layered commercial property programs assemble capacity, where each insurer participates, and what RPS says about ADAPT capacity.
Leer artículo →
Commercial Property Insurance Coverage Gaps: What a Lower Quote May Hide
A lower commercial property quote may hide larger deductibles, smaller sublimits or narrower terms. Learn how Connecticut owners can compare coverage.
Leer artículo →